Finance
Consumer lending · fintechRebuilding Trust Signals Before a Manual Action, Not After One
A compliance review flagged the exact content pattern that's preceded manual actions on other lending sites. The fix — credentialed reviewers, refreshed rate data, real disclosures — became the site's best-performing content.
- Client
- Consumer lending fintech, USA
- Timeframe
- 8 months
- Scope
- E-E-A-T remediation · Financial content compliance review · Author & reviewer credentialing · Link & citation cleanup
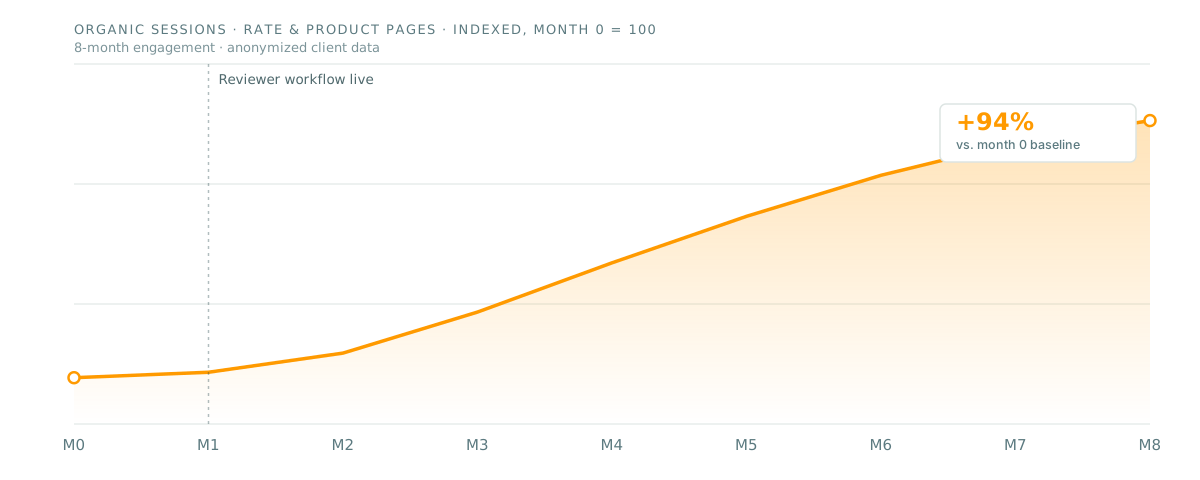
- +94%
- organic sessions to rate & product pages
- 100%
- Content library with named, reviewed authorship
- Monthly
- APR citation refresh cadence (from ad hoc)
- 0
- Manual actions in the 8 months since
The challenge
An internal compliance review, run ahead of a funding round, flagged that the site's rate and product content had no named authors, no credentialed financial reviewers, and cited APR figures that were often two or more quarters out of date.
That profile — anonymous authorship, stale rate data, no visible disclosures — closely matched sites that had received manual actions in the consumer-finance YMYL space. Nothing had happened yet, but leadership wanted it fixed before it could.
The content team had no reviewer workflow to draw on, and no process for refreshing rate data on a predictable cycle, so the same structural gaps kept reappearing in new content.
Diagnostic Transformation
The Structural Shift: Before vs. After
Inspect the baseline operational bottlenecks against the deployed compounding search infrastructure.
No named authors or credentialed reviewers on any lending or rate content
No named authors, no credentialed reviewers, and rate data that was routinely months out of date across the majority of the site.
Critical Bottlenecks Identified:
- ✕No named authors or credentialed reviewers on any lending or rate content
- ✕Over 60% of rate pages citing APR figures more than two quarters old
- ✕No visible financial disclosures or methodology notes anywhere on the site
Every rate and product page now carries a named author and a credentialed financial reviewer
Every rate and product page now carries a named author, a credentialed reviewer, and rate data refreshed on a visible monthly cycle.
Engineered Infrastructure Wins:
- ✓Every rate and product page now carries a named author and a credentialed financial reviewer
- ✓APR and rate data moved to a monthly refresh cycle with visible 'last updated' dates
- ✓Compliance signed off the full content library ahead of the funding round
Approach
Treat this as a compliance project with an SEO payoff, not the reverse
Every decision was checked against the compliance team's own risk criteria first. The ranking improvements followed from getting that right, rather than the other way around.
Get real credentialed reviewers in the workflow, not just bylines
Three credentialed financial reviewers were recruited and onboarded into an actual editorial review step, with sign-off required before any rate or product page could publish.
Rebuild the pages Google's own guidance describes for YMYL finance
Author credentials, reviewer credentials, methodology notes and disclosures were treated as required page elements, not optional trust badges.
What was executed
- Full content audit against Google's finance YMYL guidance, cross-checked with legal and compliance
- Recruited and onboarded 3 credentialed financial reviewers into the editorial workflow
- Rewrote author bio and reviewer bio templates with verifiable credentials
- Rebuilt the APR and rate data pipeline to refresh monthly with visible update dates
- Added methodology and disclosure blocks to every rate and product page
- Delivered a documentation file compliance could hand to the funding round's diligence team
“We came to this as a compliance problem. It turned into the best-performing content on the site.”
Next step
Tell me what is broken. I will tell you whether I can fix it.
I take a small number of engagements at a time so each one gets real hours. If we are not a fit, I will say so in the first reply and point you somewhere better.
- Reply time
- Within one business day
- Working hours
- US Eastern & Central overlap
- Based in
- Mirpur, Dhaka, Bangladesh